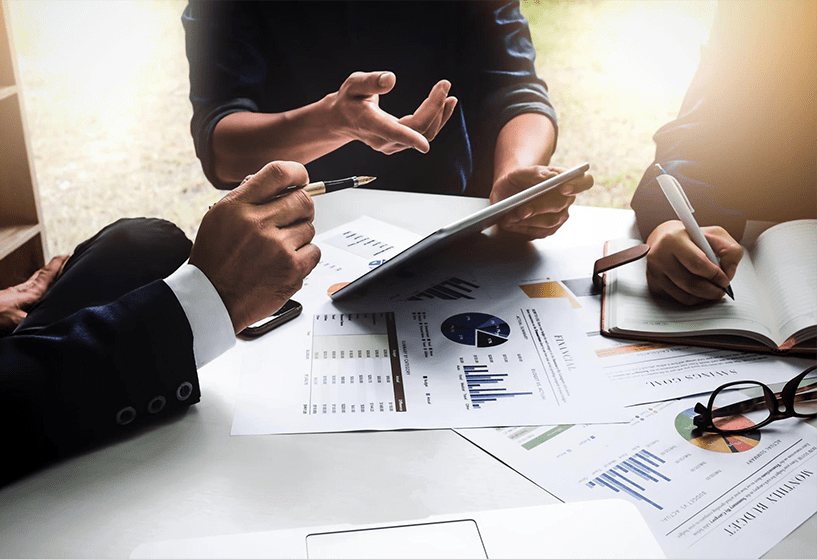
When I started freelancing, I stared at my bank statement and thought, “I need a plan.” The first step was to map out every pound that came in and went out for a full month. I used a simple spreadsheet: income on one side, fixed costs like rent, utilities, software subscriptions on the other, then variable expenses—travel, coffee, client lunches—on a third line. This gave me a clear picture of where my money actually lived.
Freelance work is irregular. I set up a “buffer fund” equal to 20% of my monthly net income and added it to my savings account each month. If a project fell through or a client delayed payment, I could dip into that fund without touching my living expenses. I also use a dedicated invoicing app that sends reminders automatically, so I rarely wait more than 14 days for payment.
Every freelancer should claim every legitimate expense. I keep receipts in a digital folder and categorize them: travel (fuel, parking), home office (electricity, internet, a proportion of rent), and professional development (online courses, conference fees). HMRC allows a flat 30% deduction for home office space if I work from home at least 50% of the time. I upload the receipts to a tax app that automatically calculates the deduction and reminds me of deadlines. That way, when it’s time to file, I’m already a step ahead.
Set a “fun budget.” I earmark 5% of my monthly income for entertainment—movies, streaming, a new video game. When I hit that limit, I either switch to a free alternative or wait until the next month. This keeps me from feeling deprived and gives me a small reward for sticking to the plan. It also helps me remember that budgeting isn’t about starving yourself; it’s about making every pound work for me.
For those who want to blend fitness with finances, check out www.bodybuildingfitness.uk for tips on staying healthy while saving.
In addition to the basics, I’ve discovered a few hacks that make a big difference. First, I use a “30‑day rule” for non‑essential purchases: if I want something, I wait 30 days. Most impulses fade, and I avoid needless debt. Second, I consolidate my credit cards into one that offers a 12‑month interest‑free period on purchases. This means I can pay off larger expenses over a year without paying extra. Third, I set up a standing order to pay my pension contribution right after each invoice is paid. It’s automatic, so I never forget, and I build a nest egg that grows tax‑free.
These habits have helped me keep a healthy savings balance, reduce stress during lean months, and still enjoy the occasional thrill of online gaming or a new console release. For example, after a month of disciplined budgeting, I was able to fund a weekend gaming marathon without dipping into my emergency fund. If you’re looking for a solid routine that blends work, play, and financial health, try the same approach—see how far a simple spreadsheet and a few rules can take you.
Absolutely, but only if it aligns with your skill set and doesn’t bleed into your main client work. I added a small side gig teaching coding workshops online. It generated an extra £300 a month, and I used that to pay down a credit card balance that had a 24% APR. The key is to keep the side hustle manageable—no more than 10% of your total hours—so you don’t burn out.
Every Friday, I spend 10 minutes reviewing the spreadsheet. I look at the variance between planned and actual spending, then adjust the next month’s budget accordingly. I also celebrate small wins: if I stay under the variable expense cap for a month, I reward myself with a new pair of headphones. This routine keeps my finances in check without turning budgeting into a chore.
There are several budgeting apps that sync with banks, but none capture the nuance of freelance income and expenses as neatly as a custom spreadsheet. The flexibility of manual entry lets me tag each line item with a project code, so I can see which gigs are most profitable. That insight guides my bidding strategy and client selection.
Budgeting as a freelancer is less about strict rules and more about visibility and flexibility. By mapping every pound, creating a buffer, automating tax and pension payments, and setting clear limits on discretionary spending, you turn uncertainty into control. Keep the spreadsheet simple, honor your “fun budget,” and review weekly. Your bank account—and your peace of mind—will thank you.
Begin by mapping every pound that comes in and goes out for a full month—split income, fixed costs, and variable expenses in a simple spreadsheet.
It reveals predictable expenses versus discretionary spend, helping you plan for recurring bills and adjust flexible items like travel or coffee.
Track income versus outgoing cash monthly; set aside a buffer for slow months and adjust variable spending to keep the gap closed.
A basic spreadsheet works, but apps like Wave, FreshBooks, or YNAB can automate tracking and visualise income versus expenses.